
Sizing the Financial Crime Team at a Payments or E-Money Firm
Payments and e-money firms face some of the heaviest financial crime workloads in UK financial services. High transaction volumes, fast onboarding, cross-border flows and constantly evolving fraud typologies mean the financial crime function has to grow at least as fast as the business, and often faster. Firms that size the team by headcount or budget rather than by risk and volume tend to find out the hard way, through backlogs, supervisory findings or restrictions on their business. This guide sets out how the team typically develops from authorisation to scale, the roles to add at each stage, and the signs it is under-resourced.
Why Payments Firms Are Different
Several features of payments and e-money businesses push financial crime workloads up:
- Volume. Thousands or millions of transactions generate large numbers of monitoring alerts.
- Speed. Faster payments leave little time to stop suspicious funds, so monitoring and decisions need to be quick.
- Fraud. Authorised push payment fraud, account takeover and mule activity are constant risks, and the mandatory reimbursement regime for APP fraud has made fraud losses a direct cost.
- Onboarding at scale. Digital onboarding of consumers or merchants needs robust automated checks and well-staffed exception handling.
- Merchants and agents. Acquirers and firms using agents or distributors take on third-party risk that needs monitoring.
- Cross-border flows. International payments bring sanctions and higher-risk jurisdiction exposure.
- Supervisory focus. The FCA has repeatedly highlighted weaknesses in payments firms’ financial crime controls, and supervisors pay close attention to them.
Our guide to the people the FCA expects payments and e-money firms to have covers the authorisation stage, and the FCA’s financial crime pages set out its broader expectations.
How the Team Typically Grows
The stages below are a guide drawn from the firms we work with. Every firm’s path depends on its model, customers and growth, so treat the triggers as prompts for review rather than fixed thresholds.
| Stage | Typical structure | Triggers to move on |
|---|---|---|
| Authorisation and launch | An experienced MLRO, often fractional and sometimes also holding SMF16; outsourced or automated screening | First customers live; alerts and onboarding exceptions start to build |
| Early growth | MLRO plus one or two analysts covering onboarding exceptions and alert review | The MLRO is reviewing cases personally; fraud losses are rising |
| Scaling | MLRO, deputy MLRO, small teams for onboarding and monitoring, a fraud lead | Backlogs persist; new markets or products; sanctions exposure grows |
| Established | Head of financial crime (possibly SMF17), leads for AML operations, fraud, sanctions and investigations, plus QA and testing | Enhanced status, banking partner scrutiny, large-scale operations |
Stage One: Authorisation and Launch
At authorisation, the FCA wants to see a credible MLRO who has helped design the controls described in the application: the business-wide risk assessment, onboarding standards, monitoring scenarios and reporting process. Many firms appoint a fractional MLRO at this stage, sometimes holding SMF16 too. That works if the person has genuine payments experience and the time commitment reflects the planned volumes, not just today’s. Our page on fractional MLRO recruitment covers how to scope it.
The common mistake at launch is assuming automated tools will carry the load. Tools generate alerts and exceptions; people have to resolve them. Plan for the first analyst before go-live, not after the first backlog.
Stage Two: Early Growth
Once the firm has real customers and transaction volumes, the MLRO’s time quickly gets absorbed by case work. The first hires are usually one or two analysts to handle onboarding exceptions, enhanced due diligence and first-level alert review, so the MLRO can focus on decisions, the risk assessment and board reporting. If the MLRO is fractional, this is often the point where the firm needs someone inside the business to handle escalations on the other days.
Fraud usually becomes a distinct workload here too. Rising APP fraud claims and mule activity need someone who understands fraud typologies, reimbursement obligations and data, even if they also cover some AML work.
Stage Three: Scaling
As volumes grow, the function needs management as well as analysts. The typical additions are:
- A deputy MLRO to run day-to-day operations, provide cover for reporting decisions and build succession. Our guide to deputy MLROs explains the role.
- A fraud lead to own fraud prevention, detection and reimbursement processes.
- Team leaders for onboarding and monitoring as analyst numbers grow beyond what one person can supervise.
- A sanctions specialist where cross-border flows or international customers create significant exposure. Our guide to hiring a sanctions lead covers when and why.
At this stage, a combined compliance officer and MLRO usually needs to be split, or at least supported by a strong deputy. Our guide to when to split a combined SMF16 and SMF17 role sets out the signs.
Stage Four: Established
Larger payments and e-money firms typically run a structured financial crime function led by a head of financial crime, who may hold SMF17 or report to an MLRO with broader oversight. Specialist teams cover AML operations, fraud, sanctions and investigations, with a separate quality assurance or testing function checking that controls work in practice. Our guide to head of financial crime or MLRO explains how the senior roles fit together.
Signs the Team Is Under-Resourced
- monitoring alerts or onboarding exceptions waiting more than a few days for review
- periodic customer reviews overdue
- the MLRO personally reviewing routine cases
- rising fraud losses or APP reimbursement claims without a clear owner
- monitoring rules that haven’t been reviewed since launch
- banking or scheme partners raising questions about controls
- growth targets set without a corresponding financial crime resourcing plan
- supervisory or audit findings on financial crime
Banking partners deserve particular mention. Payments firms rely on banks for safeguarding accounts and payment access, and banks conduct their own due diligence on the firm’s financial crime controls. A weak function can cost a firm its banking relationships well before the regulator acts.
Scenario: An e-money institution offering business accounts grows from 2,000 to 15,000 customers in eighteen months. Its financial crime team is still the fractional MLRO and two analysts it had at launch. Alerts wait three weeks for review, periodic reviews are months overdue, and its banking partner asks for a remediation plan after spotting mule activity in its flows. The firm appoints a full-time MLRO with payments experience, adds a deputy MLRO and a fraud lead, and brings in interim analysts to clear the backlog. It also introduces a resourcing model linking financial crime headcount to customer and transaction growth, reviewed quarterly by the board.
Building a Resourcing Model
The firms that manage this well link financial crime resourcing to the drivers of the work, rather than setting headcount in an annual budget and hoping. A simple model tracks:
- new customers onboarded per month and the share needing manual review;
- alerts generated per month and the average time to resolve each;
- fraud cases and reimbursement claims;
- periodic reviews due, by customer risk rating;
- internal suspicion reports and SARs; and
- planned growth in each of these.
From that, the firm can estimate analyst capacity needed and the management layer to supervise it, and show the board and the regulator a clear rationale. Review it quarterly, and whenever a new product or market launches.
Recruiting for Payments Financial Crime
Experienced payments financial crime professionals are in high demand, and the best MLROs and deputies in the sector are rarely on the market for long. Sector experience matters: fraud typologies, scheme rules, safeguarding interactions and the pace of payments operations are hard to learn on the job at senior level. Our page on SMF recruitment for payments and fintech covers the market, and our financial crime leadership recruitment practice recruits deputy MLROs, heads of financial crime, fraud and sanctions leads. For the MLRO itself, see our page on MLRO recruitment.
Payments Financial Crime Recruitment
Teams that keep pace with growth. Every SMF search is led personally by Adrian Lawrence FCA
Financial Crime Team
Deputies, heads and specialists.
→ Financial crime leadership → Deputy MLROsHiring a sanctions lead →
MLRO
Full-time or fractional SMF17.
→ SMF17 recruitment → Fractional MLROHead of financial crime or MLRO? →
Payments Sector
Authorisation to scale.
→ Payments and fintech → Authorisation supportPI and EMI people guide →
Interim Cover
Backlogs and remediation.
→ Interim MLRO and compliance → Joint SMF16 and SMF17Staffing a remediation →
Every SMF search is led personally by Adrian Lawrence FCA
Frequently Asked Questions
Is there a standard ratio of financial crime staff to customers?
No. It depends on the business model, customer risk, automation and alert quality. A resourcing model based on actual workloads is far more reliable than a ratio.
Can a newly authorised payments firm use a fractional MLRO?
Yes, and many do. The time commitment should reflect planned volumes, and the firm needs someone internal to handle escalations on other days.
Should fraud sit with the MLRO?
In most payments firms, fraud and AML sit together in one financial crime function because the data and typologies overlap. What matters is clear ownership.
How quickly can you add capacity?
Interim analysts and specialists can usually start within weeks. Permanent senior hires typically take two to four months, plus FCA approval for SMF17.
About the Author
Adrian Lawrence FCA is the founder of SMF Capital. He is a Chartered Accountant and Fellow of the ICAEW, holds a practising certificate in his own name, and is a former listed-company Finance Director with a BSc from Queen Mary College, University of London. He founded FD Capital in 2018 and has since built a network of five specialist recruitment practices. He leads every SMF Capital search personally. View Adrian’s ICAEW profile.
Growing a Payments Firm?
Tell us about your volumes, customers and growth plans. We’ll help you plan your financial crime team and find the MLRO, deputy and specialists to run it. We’ll come back to you the same working day.
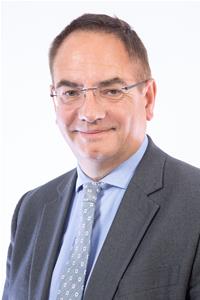
Adrian Lawrence FCA is the founder of SMF Capital and a Fellow of the Institute of Chartered Accountants in England and Wales and holds an ICAEW practising certificate in his own name. He holds a BSc from Queen Mary College, University of London, and has over 25 years of experience working with boards, investors and business owners across the UK. He founded SMF Capital to help FCA and PRA-regulated firms appoint the Senior Managers the regulators expect, with the fit and proper assessment built into every search, and personally leads every Senior Manager Function search.