Leaving a Network: A 12-Month Plan for Insurance Brokers
Plenty of brokers start life as an appointed representative of a network. It is a sensible way to begin: the principal holds the permissions, provides compliance support and takes regulatory responsibility. But as a book grows, the fees, restrictions on panels and lack of control over your own brand start to bite, and going directly authorised becomes attractive. This post sets out a realistic 12-month plan for that move, with the people decisions in the right order. Most of the delays we see come from late hiring rather than from the FCA.
Before You Start: Is Now the Right Time?
Going directly authorised (DA) means taking on everything your network currently does for you: compliance monitoring, complaints handling, financial promotions sign-off, client money, regulatory reporting and the cost of the FCA, FOS and FSCS levies. It suits brokers with a stable book, clear plans and the appetite to run a regulated business. It is less suited to a firm that is still finding its feet or depends on the network for placing power. If you are unsure, start with our guide to how the appointed representative model works and talk to your network about what leaving would involve under your contract.
Questions to Ask Your Network Before Giving Notice
- What notice period applies, and can you keep trading as an appointed representative while your application is assessed?
- Who owns the client records, and how will files, complaints history and claims in progress be handed over?
- Will the network’s insurer agencies continue for renewals during the transition, or do you need your own from day one?
- Are there any restrictive covenants or fees for leaving?
- Which open file reviews, complaints or breaches need to be closed before you go?
Months 1 to 2: Decide the Shape of the Firm
- What you will sell: commercial, personal lines or both, and whether any long-term insurance is in the mix. This decides whether you are within the Money Laundering Regulations. See does a general insurance broker need an MLRO?
- Your SMCR category: most small directly authorised brokers are Core firms, which means a Chief Executive or executive director, a compliance oversight function (SMF16), and an MLRO (SMF17) if you are in scope.
- Client money: whether you will hold it, under risk transfer or under CASS 5, and if so whether a statutory or non-statutory trust. This drives your capital requirement. See CASS 5 for insurance intermediaries.
- Your timeline with the network: notice periods, ownership of client records and how renewals will move across.
Months 2 to 4: Appoint Your Compliance Officer
This is the hire that most often comes too late. Your SMF16 needs to be in place, or at least committed, before the application is written, because the FCA will assess them as part of it and they should shape your compliance framework. For most small brokers the right answer is a part-time or outsourced compliance officer with broker experience, typically one to two days a week to begin with. See compliance officer for insurance brokers, outsourced compliance officer and fractional or full-time compliance officer?
Look for someone who has been through a DA application before, knows ICOBS, PROD and the Consumer Duty as they apply to brokers, and can handle client money oversight and financial crime. Ask them what went wrong on the last application they worked on. A good candidate will have a clear answer.
Months 3 to 5: Build the Application
With your compliance officer in place, build the application package:
- a regulatory business plan that explains your products, customers, distribution and how you will deliver good outcomes;
- financial projections showing you will meet capital requirements with headroom;
- professional indemnity insurance meeting the minimum limits in MIPRU;
- a compliance monitoring plan, policies and procedures;
- Form A applications for each Senior Manager, a Statement of Responsibilities and a Management Responsibilities Map if required; and
- an explanation of how you will handle client money and complaints.
Our guides to threshold conditions and Part 4A permission and what goes wrong in Form A submissions cover the common weak spots.
Months 5 to 11: The FCA Assessment
The FCA must decide a complete application within six months, and an incomplete one within twelve. In practice, the clock is reset by questions, and a broker with a thin business plan or an inexperienced compliance officer can expect more of them. Use this period productively:
- agree TOBAs and agencies with insurers so you can trade on day one;
- set up your client money bank accounts and acknowledgement letters if needed;
- finalise systems, file reviews and the complaints process;
- plan how clients will move across from the network and how you will communicate with them; and
- prepare staff for the Conduct Rules and the training they will need, including the 15 hours a year of IDD continuing professional development.
Month 12: Go Live
Once authorised, the work changes from building to running. In the first quarter your compliance officer should deliver the first monitoring report to the board, check the first client money reconciliations, review the first complaints and confirm that regulatory returns are scheduled. Our guide to the first 90 days sets out what good looks like.
| Month | Main tasks | People decision |
|---|---|---|
| 1–2 | Products, SMCR category, client money model, network exit terms | Decide roles needed |
| 2–4 | Compliance framework outline | Appoint compliance officer (and MLRO if needed) |
| 3–5 | Business plan, financials, policies, Form As | Confirm directors and Senior Managers |
| 5–11 | FCA assessment, insurer agencies, systems | Train staff, plan cover for absence |
| 12 | Go live, first monitoring and reconciliations | Review the compliance officer’s days per week |
What Usually Causes Delay
- Appointing the compliance officer after the application is written: the FCA can tell when a framework has been bought rather than owned.
- A compliance officer with no broker experience: strong conduct background from banking or wealth doesn’t always translate to ICOBS, client money and insurer relationships.
- Unclear client money arrangements: the FCA will ask exactly how premiums and claims money will flow.
- Thin financial projections: especially for the first year, when commission from renewals may arrive more slowly than expected.
- Late conversations with insurers: some won’t grant agencies until authorisation is confirmed, so build in time.
Scenario: A commercial broker with eight staff decides to leave its network. It plans to submit its application in month two, with a compliance consultant writing the documents and a compliance officer to be found later. We suggest reversing the order. The firm appoints a fractional SMF16 with two previous DA applications behind them, who rewrites the business plan, simplifies the client money arrangements to risk transfer only and drafts a monitoring plan the broker can actually deliver. The application goes in a month later than first planned but with a much stronger story.
Budgeting for the People
The biggest new cost of going DA is usually people rather than fees. Budget for a part-time compliance officer, possibly an MLRO, some external compliance monitoring support and time from your directors. Our salary guide and combined compliance officer and MLRO costs give typical ranges.
The Bottom Line
Leaving a network is very achievable, but it rewards brokers who make the people decisions early. Settle your products and client money model, appoint a compliance officer with broker experience, then build the application around them. For the full checklist, see becoming a directly authorised insurance broker.
Going Directly Authorised
The roles you will need. Every broker search is overseen by Adrian Lawrence FCA
Brokers
Compliance for brokers and MGAs.
→ Compliance officer for brokers → Outsourced compliance officerBecoming a DA broker →
Authorisation
Building the team.
→ SMF authorisation support → Going DA: senior managersBuilding an SMF team →
Client Money
CASS for brokers.
→ CASS 5 explained → CASS oversightClient money: five decisions →
Small Firms
Part-time options.
→ Part-time compliance officer → Fractional MLROInsurance SMF recruitment →
Every broker search is overseen by Adrian Lawrence FCA
Frequently Asked Questions
How long does it take to leave a network and go directly authorised?
Around 12 months is realistic, including preparation and an FCA assessment that can take up to six months for a complete application.
When should we appoint our compliance officer?
Before the application is written. The FCA assesses them as part of it and they should shape your compliance framework.
Can our compliance officer be part-time?
Yes. Many small brokers use a part-time or outsourced compliance officer, typically one to two days a week to start.
Do we need an MLRO?
Only if you are within the Money Laundering Regulations, which for brokers usually means arranging long-term insurance.
What causes the most delay?
Late hiring, inexperienced compliance officers, unclear client money arrangements and thin financial projections.
About the Author
Adrian Lawrence FCA is the founder of SMF Capital. He is a Chartered Accountant and Fellow of the ICAEW, holds a practising certificate in his own name, and is a former listed-company Finance Director with a BSc from Queen Mary College, University of London. He founded FD Capital in 2018 and has since built a network of five specialist recruitment practices. He oversees every SMF Capital search. View Adrian’s ICAEW profile.
Planning to Leave Your Network?
Tell us your timeline and what you sell. We’ll suggest the right compliance officer set-up and come back with a plan the same working day.
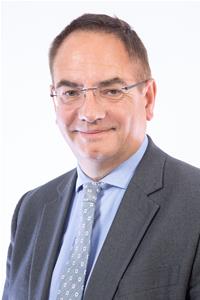
Adrian Lawrence FCA is the founder of SMF Capital and a Fellow of the Institute of Chartered Accountants in England and Wales and holds an ICAEW practising certificate in his own name. He holds a BSc from Queen Mary College, University of London, and has over 25 years of experience working with boards, investors and business owners across the UK. He founded SMF Capital to help FCA and PRA-regulated firms appoint the Senior Managers the regulators expect, with the fit and proper assessment built into every search, and personally leads every Senior Manager Function search.